
WHSmith FY26 profit before tax has come in at £75m ($100.4m), unaudited and down from £108m ($144.6m) a year earlier, as airport revenue growth failed to offset thinner margins and a widening exit from loss-making markets.
WHSmith has confirmed its unaudited FY26 headline group profit before tax will come in at £75m ($100.4m), down from £108m ($144.6m) the previous year, according to a trading update reported by TRBusiness on 18 September 2026. The UK-headquartered travel retailer, which trades airside across the UK, North America and mainland Europe, issued the figure ahead of preliminary results due on 12 November 2026.
The number matches WHSmith’s revised guidance but sits £33m below last year’s outturn, a gap the group attributes to heavier promotional discounting, reduced brand marketing spend, inflationary cost pressure and lower trading margins. Fourth-quarter (June to August) group revenue still rose 5% year on year, and the divisional split shows where that growth, and the margin pressure, actually landed.
| Division | Q4 revenue vs prior year | Q4 like-for-like |
|---|---|---|
| UK | +7% | +4% |
| North America (total) | +5% | -3% |
| North America airports | +13% | -2% |
| Resorts | -26% | n/a |
| Rest of World | -4% | +3% |
Source: WHSmith trading update, as reported by TRBusiness, 18 September 2026.
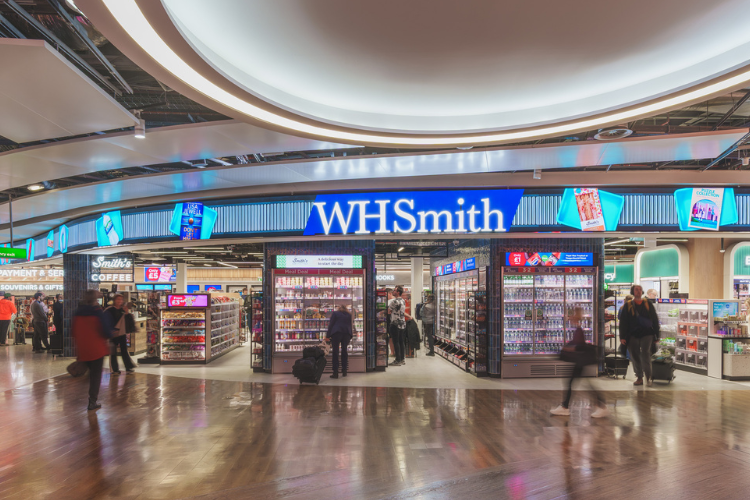
The UK was the strongest performer, helped by six new one-stop shops opened during the year, including a refurbished flagship at London Heathrow plus outlets at Liverpool, Belfast International and East Midlands. The format mirrors a wider push toward higher-spend combined retail units, the same logic behind Gatwick’s largest-ever food and beverage tender covering 3,800 square metres across six units and Gebr. Heinemann’s expanded retail footprint at Berlin Brandenburg.
North America airports delivered 13% Q4 revenue growth on continued investment in the group’s travel essentials format, though like-for-like sales there fell 2%, and total North America like-for-like dropped 3% as the InMotion electronics chain lost further ground. WHSmith blames lower year-on-year passenger volumes and softer consumer demand for the airport channel’s like-for-like decline.
Resorts was the weakest channel, with Q4 revenue down 26% year on year as visitor numbers fell and WHSmith accelerated the wind-down of its fashion estate, leaving 74% of the division’s prior-year revenue intact. Rest-of-World revenue fell 4% overall despite 3% like-for-like growth, as an aggressive portfolio restructuring continues: WHSmith has already departed Norway, has agreed to exit Denmark and Sweden in early 2027, and will leave Amsterdam Schiphol Airport on lease expiry in 2027 after deciding not to re-tender the contract, a move that lands as Schiphol works through a separate ground handling tender dispute now heading to court.
For airports, the split matters more than the headline number. Where WHSmith is investing, UK one-stop shops and North American travel essentials, it is competing hard for footprint and rent uplift, which strengthens landlords’ hand in renewal talks. Where it is retreating, Schiphol, the Nordics, its resorts fashion estate, concession teams should start scouting replacement operators now rather than waiting for lease expiry, watching how rivals such as SSP Group, currently restructuring its own strategy leadership, respond to the space being vacated.
Airports with a WHSmith lease due for renewal before 2027 should ask now whether the group intends to renew or move the site to a franchise model, given its stated preference under this restructuring. Those already on WHSmith’s exit list, Schiphol chief among them, have roughly 12 months to run a competitive retender rather than default to a straight renewal. Full audited figures follow at WHSmith’s preliminary results on 12 November 2026, and the original trading update is available via TRBusiness.
Image: trbusiness.com